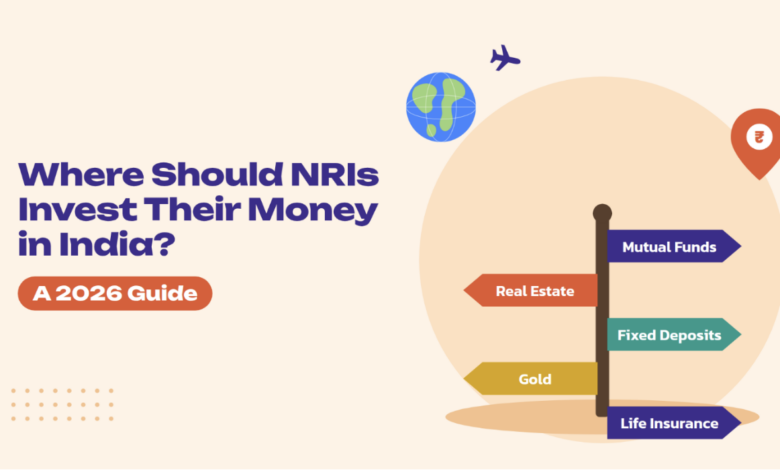
NRIs may consider investing in India to address goals such as retirement, family responsibilities, education or long-term wealth creation. Their investment choices can include bank deposits, mutual funds, bonds, real estate and insurance-linked products, subject to eligibility and applicable regulations. The choice depends on factors such as investment horizon, risk tolerance, liquidity requirements, tax treatment, and residential status. Understanding these factors can provide context before allocating money across different options. This article examines investment options available to NRIs in India and factors that shape these choices.
Investment Options Available to NRIs in India
NRIs have access to several investment avenues in India, although eligibility, account requirements and regulatory conditions may differ across products. Life insurance can form part of this financial planning where protection needs exist alongside long-term financial objectives.
Bank Fixed Deposits
NRIs may invest through NRE, NRO or FCNR deposit accounts, subject to applicable banking and regulatory conditions. These deposits differ in currency, repatriation rules, taxation and interest treatment.
The choice of account can therefore depend on the source of funds, intended use and whether the money may need to be transferred outside India.
Mutual Funds
NRIs can invest in eligible mutual fund schemes in India, subject to applicable regulations and the fund house’s requirements. Mutual fund returns are linked to the performance of the underlying securities and therefore carry market-related risk.
Investment objectives, time horizon, risk tolerance, and taxation can be considered when assessing this option.
Bonds and Government Securities
NRIs may have access to certain bonds and government securities under applicable regulations. These instruments differ in terms of issuer, maturity, interest payments, credit risk, and market risk.
The specific eligibility and investment route can depend on the security and the investor’s residential status.
Real Estate
Real estate may form part of an NRI’s India-focused investment strategy, subject to applicable rules governing property ownership and transactions.
Unlike financial investments, property generally involves a larger initial allocation and may have lower liquidity. Location, property type, financing, maintenance, and taxation can affect the financial outcome.
Life Insurance and Investment-Linked Products
Certain life insurance products combine financial protection with savings or market-linked investment features. These products have a different structure from standalone investment products and may involve policy-specific charges, terms, and conditions.
NRIs assessing such products can consider their protection requirements separately from their investment objectives.
How NRIs Can Assess Different Investment Options
The appropriate investment mix depends on the purpose for which the money is being allocated. Comparing products across a few core factors provides a more consistent basis for assessment.
| Factor | What NRIs Can Consider |
| Investment goal | Retirement, education, family needs or wealth creation |
| Time horizon | When the invested funds may be required |
| Risk tolerance | Capacity to withstand market or value fluctuations |
| Liquidity | How quickly funds may need to be accessed |
| Repatriation | Whether funds may need to be transferred outside India |
| Tax treatment | Applicable Indian and overseas tax rules |
| Currency exposure | Potential effect of exchange-rate movements |
NRE, NRO and FCNR Accounts: Why the Difference Matters
The type of bank account used can affect how an NRI holds and manages money in India.
NRE Account
NRE accounts are maintained in Indian rupees and are generally used for holding overseas earnings in India. Applicable rules govern interest, taxation, and repatriation.
NRO Account
NRO accounts can be used to manage income earned in India, such as rent or pension. Taxation and repatriation rules applicable to these accounts differ from NRE accounts.
FCNR Account
FCNR deposits are maintained in specified foreign currencies, which can reduce direct exposure to fluctuations between the foreign currency and the Indian rupee for the deposited amount, subject to applicable terms.
Tax and Repatriation Considerations for NRIs
Tax treatment can depend on residential status, investment type, income source and applicable Indian tax provisions. NRIs may also need to consider taxation in their country of residence.
Repatriation rules can differ according to the investment and the account through which funds are held. Reviewing the applicable conditions before investing can provide clarity about how and when funds may be transferred abroad.
Advantages and Limitations of Investing in India as an NRI
The following table outlines the advantages and limitations that NRIs may consider when assessing an NRI investment plan in India:
| Advantages | Limitations |
| Provides access to Indian investment opportunities | Eligibility and regulatory conditions may apply |
| Can support India-linked financial goals | Currency movements may affect overseas value |
| Offers different investment categories | Tax treatment can vary by product and residence |
| May support family-related financial requirements in India | Repatriation rules differ across investments |
| Allows diversification across selected asset classes | Market-linked products may experience value fluctuations |
Conclusion
NRIs can consider several investment options in India, including deposits, mutual funds, bonds, real estate and selected insurance-linked products. Tata AIA provides life insurance and investment-linked options that eligible NRIs may assess alongside other financial avenues, subject to policy terms, underwriting requirements and applicable regulations. The choice of investment can depend on financial goals, time horizon, risk tolerance, liquidity, taxation, repatriation requirements, and currency exposure. Reviewing these factors together can provide a broader basis for structuring India-focused investments.

